Specialist PBSA finance across the UK, built for September.
We arrange development finance, forward funding, stabilisation and investment debt for PBSA (purpose-built student accommodation). Every structure is tested against one date: the start of the academic year.
An initial conversation with the principal. No obligation to proceed.
We arrange unregulated commercial finance and are not a lender. Lenzie Consulting Ltd is not authorised or regulated by the FCA; regulated cases are referred to a regulated firm.
 Purpose-built student accommodation Site to refinance.Debt and equity for every stage of a scheme.
- Development finance, forward funding and investment debt
- Unregulated commercial finance
- Developers, operators and investors
What is PBSA? One asset, two sets of risks.
PBSA stands for purpose-built student accommodation. PBSA is residential accommodation designed, built and managed for students, usually let by the bed on academic-year tenancies of 44 to 51 weeks.
In real estate terms, lenders treat it as an operational asset. Its value rests on rents, occupancy and the operator as much as on bricks and mortar, so a PBSA facility is underwritten on both the building and the business that runs it, unlike a loan on a student HMO. Schemes range from 100-bed studio blocks to 1,000-bed towers of cluster flats, let direct to students (direct let) or to a university under a nomination agreement. The room mix and income type shape the facility: a studio block on direct let income is usually sized on a more cautious occupancy case than cluster flats with nominations in place.
Read the full PBSA guide ↗Purpose-built student accommodation funding, from site to refinance.
A scheme moves through six funding stages. Each has a different lender pool, a different leverage test and a different exit.
- 01Site and bridgingShort-term debt to buy a site or hold it through planning.
- 02DevelopmentSenior development finance, sized on cost and value, drawn monthly.
- 03Forward fundingAn investor funds the build and takes the completed asset.
- 04StabilisationBridge from practical completion to a fully let first year.
- 05InvestmentTerm debt or acquisition finance on an operating, let asset.
- 06RefinanceRelease equity or replace a maturing facility on trading figures.
One mandate. A competitive process.
Large PBSA facilities, from development finance to investment loans, are won on preparation. We build the credit case once, take it to the lenders active in student accommodation for that stage, and negotiate the terms side by side, so you choose between real offers rather than indications.
We are an arranger and introducer, not a lender. Terms are subject to status, valuation and lender criteria.
- 01 Read the schemeAppraisal, cost plan, planning, programme and the demand case, tested before any lender sees it.
- 02 Structure the capital stackSenior, stretch, mezzanine or joint-venture equity, sized to the stage and the exit.
- 03 Run a competitive processA credit-ready pack taken to the lenders active in PBSA for that stage, in parallel.
- 04 Negotiate heads of termsLeverage, pricing, covenants, conditions and exit compared side by side.
- 05 Deliver to drawdownValuation, monitoring surveyor, legals and conditions precedent through to first draw.
How lenders size PBSA debt, and why the term date matters.
Student accommodation lenders size senior loans on several tests at once and lend the lowest answer: loan to cost and loan to gross development value for PBSA development finance, and loan to value and interest cover or debt yield for investment loans on an operating asset.
Students sign for a full academic year. A scheme that completes in October has missed its first intake and earns little until the following September, so lenders test the programme against the term date and look closely at lettings velocity from January onwards.
- Demand: students against beds, and walking time to campus.
- Planning and safety: sui generis consent, Section 106 terms and Gateway 2.
- Delivery: a fixed-price contract and a programme that beats September.
- Operator and exit: who lets the beds, their occupancy record, and what repays the loan.
What types of PBSA funding are available, and which fits your scheme?
PBSA finance is a family of commercial property finance products. The right one depends on where the scheme sits in its life.
PBSA financing is a family of commercial real estate and property finance products, each built for one stage of a student accommodation project. The right facility depends on where the scheme sits: a site without planning, a consented scheme drawing development finance, a newly completed block letting its first year, or an operating asset with a trading history.
| Finance type | Best suited to | Typical exit |
|---|---|---|
| Bridging finance | Buying a site or an operating block quickly, or holding a site through planning | Development finance, sale or term debt |
| Development finance | Funding construction of a consented student scheme, drawn monthly against certified works | Forward sale, stabilisation or investment debt |
| Forward funding | Developers selling the finished scheme to an institutional investor who funds the build in place of development finance | Completion and handover to the investor |
| Stabilisation finance | A completed block repaying its development finance in the first letting year, before occupancy is proven | Investment debt or sale |
| Investment finance | Acquiring or holding an operating, let PBSA asset or portfolio | Refinance or sale |
| Refinance | Replacing a maturing facility or releasing equity on trading figures | A new term facility |
| Mezzanine and JV equity | Closing the gap between senior development finance and the developer's own equity | Repaid from sale or refinance |
Most PBSA projects, from London to Glasgow, use more than one: development finance to build, stabilisation finance to let, and investment finance to hold. We plan that sequence at the start, so the terms of each facility fit the exit of the one before it.
What a developer should consider when securing student accommodation finance
- Location and demand. Lenders favour cities with a deep, growing student body, especially those with Russell Group and other research-intensive universities, a high share of international students and a shortage of beds against full-time students.
- Leverage against cost and value. Development finance is sized on loan to cost and capped on loan to GDV. Stretching development finance beyond that usually means adding mezzanine or JV equity, at a higher blended cost.
- The programme. A realistic build programme with contingency, measured against the September term, matters as much as the pricing.
- The exit. Securing a forward sale, a stabilisation line or an investment lender in principle before construction starts makes development finance easier to raise.
- Room mix and income. A studio-led scheme relying on direct let income is sized on a lower occupancy and rent case than one with a university nomination agreement covering part of the beds.
- Pricing and fees. Commercial PBSA loans, from development finance to term debt, are priced over SONIA or the swap rate according to leverage, stage and sponsor, with arrangement and exit fees on top.
The UK student accommodation market, in four numbers.
UK PBSA investment reached £2.3bn in H1 2026 (Knight Frank).
Make your next move an informed one.
Our PBSA guides explain how lenders test student schemes, from planning and Gateway 2 to yields and lender appetite.
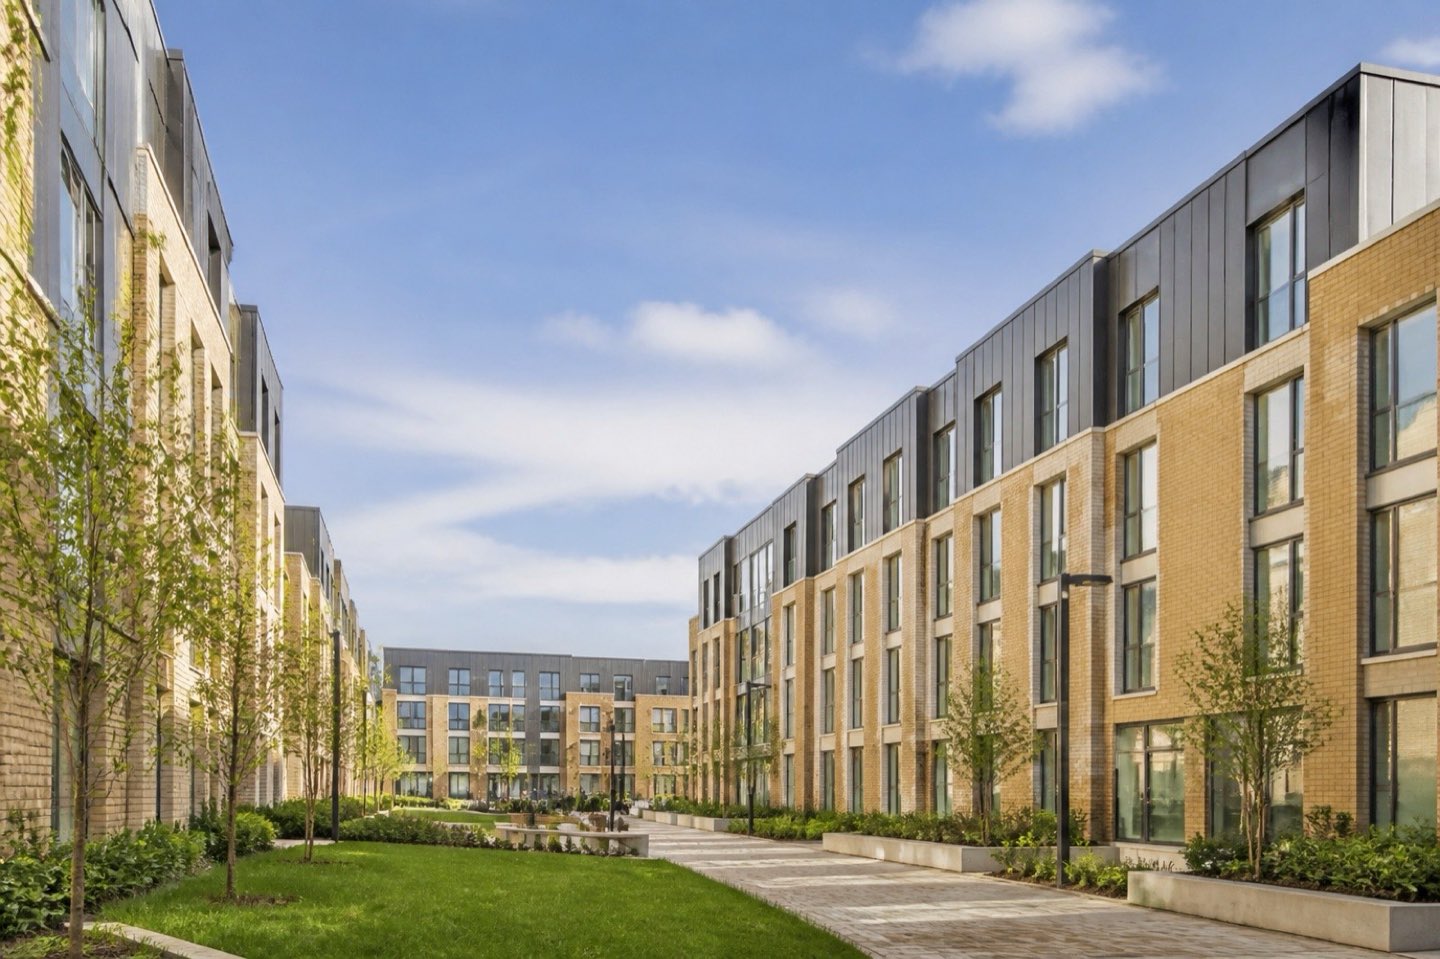
PBSA lending across England, Scotland and Wales, city by city.
Each city page sets out student demand, the planning pipeline and rent evidence for that university city, with every source dated and named.
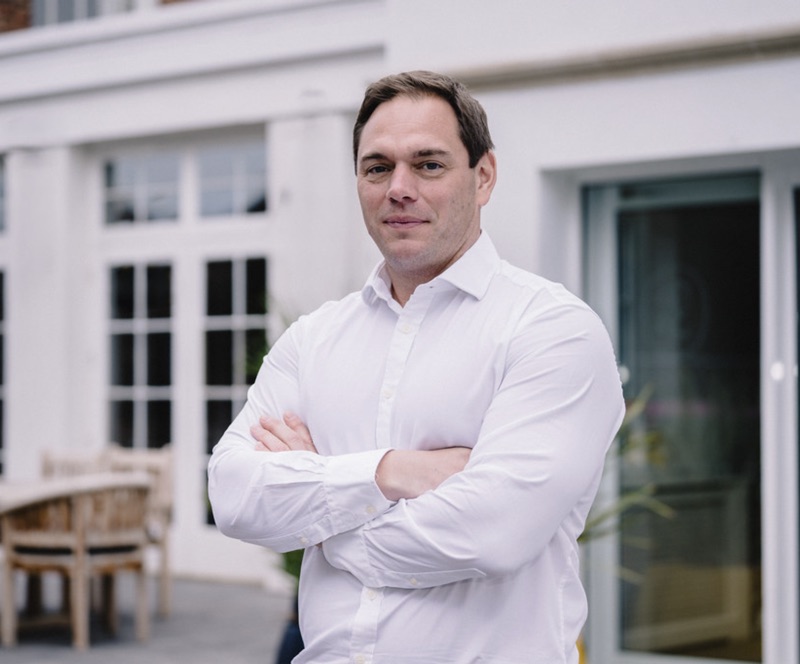
One principal, from first model to drawdown.
Matt Lenzie has 25 years in financial services, raising debt and equity, with significant transactional experience including the sector, and has arranged around £400m of funding. Every mandate is structured and run by Matt personally, from the first appraisal review to the final drawdown. There is no junior desk and no hand-off.
About us ↗PBSA finance, made simpler.
The questions developers, operators and investors ask before the first call.
Ask about your scheme ↗What does PBSA mean in property?
What is a PBSA scheme?
How much can you borrow for a PBSA development?
Why invest in PBSA?
Do you lend the money yourselves?
Are you regulated by the FCA?
What's your next scheme?
Send the appraisal. We reply within one working day with how the lenders active in PBSA are likely to size it.