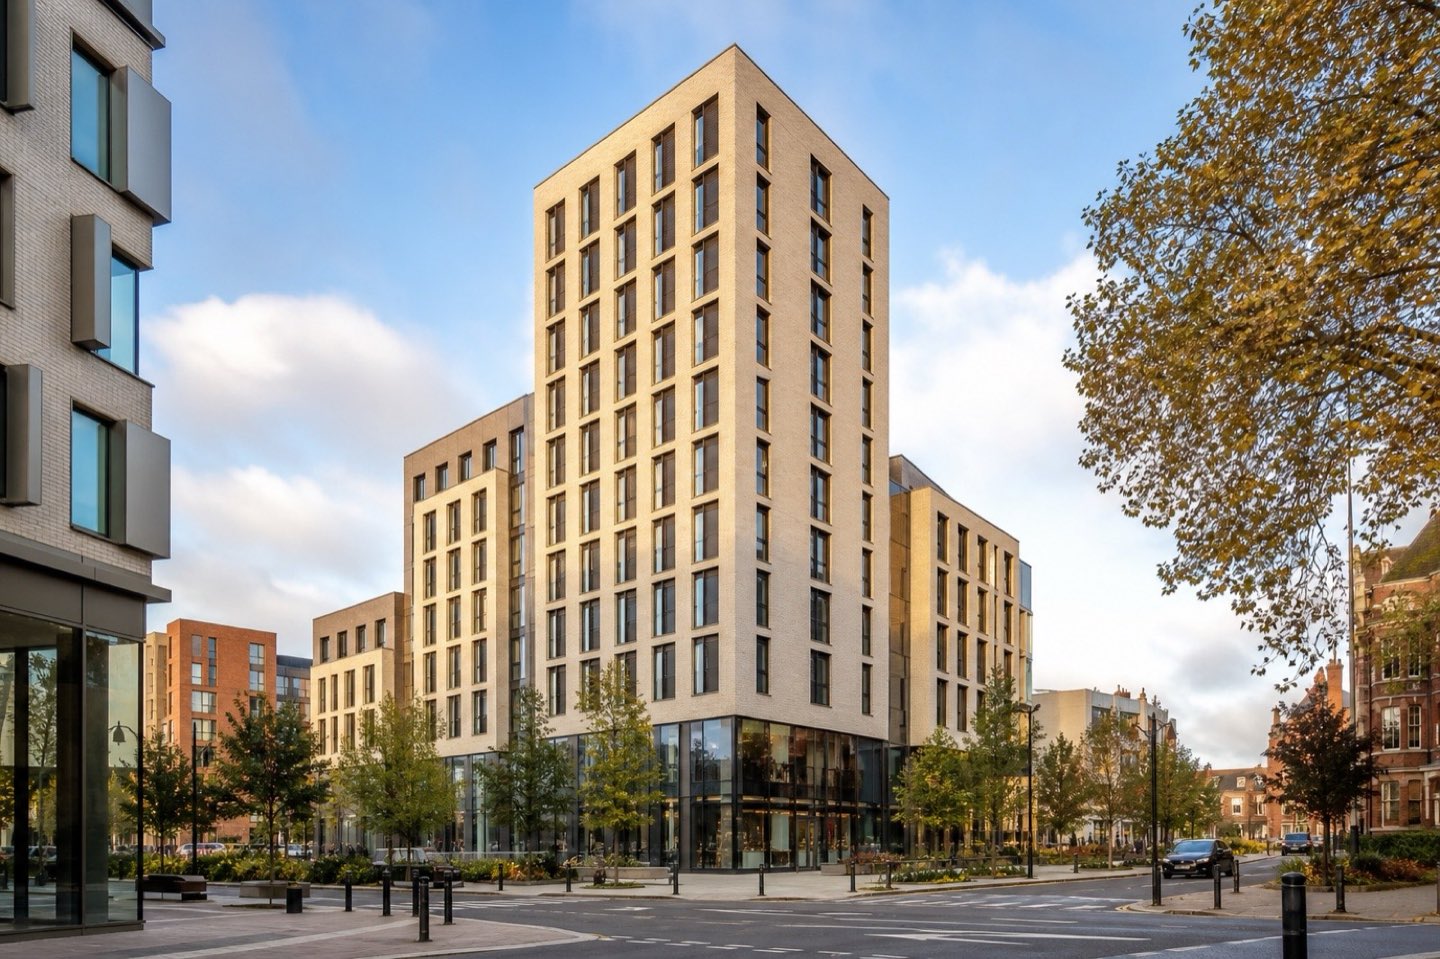
Institutional PBSA investment rests on structural undersupply, strong historic occupancy and rental growth, and a deep, liquid market. The risks are real: oversupply in some cities, international student policy, affordability, new regulation, building safety costs and dependence on the operator. Buying a single student room through a retail scheme is a very different proposition. We do not provide investment advice.
What does investing in student property actually mean?
PBSA investment means owning, or lending against, a managed building of student rooms whose value depends on the income it earns. That income is rent per bed per week, less operating costs, across an academic year. It is an operational real estate investment, closer to a hotel than to a buy-to-let flat, and it sits alongside build to rent in the wider living sector of property investment.
There are two very different ways into the market, and most of the confusion around 'is student accommodation a good investment' comes from mixing them up:
| Institutional PBSA | Retail 'buy a room' scheme | |
|---|---|---|
| What you own | A whole building or portfolio, or shares in a listed owner | A long lease of one room within a building |
| Typical investors | Pension funds, REITs, private equity, insurers, sovereign wealth | Private individuals, often overseas |
| Due diligence | Independent valuation, legal, technical and operator review | Often limited to the seller's marketing pack |
| Income | Actual net operating income of the building | Often a promised or 'assured' fixed return |
| Exit | Institutional buyers and a deep investment market | Few buyers; lenders rarely lend on single rooms |
| Finance | Development, stabilisation and investment debt | Usually cash only |
The rest of this guide looks mainly at institutional PBSA, the market we arrange finance in, before setting out the specific risks of retail schemes.
What are the advantages of purpose-built student accommodation for investors?
High demand and structural undersupply
Savills found 2.7 full-time students for every PBSA bed across 20 major markets, and estimated that an extra 234,000 beds would be needed to bring that ratio down to 1.5 (Savills, April 2024). Demand is still growing: a record 695,740 applicants had applied to UK universities by the June 2026 UCAS deadline, up 4% on the year, with international undergraduate applicants up 7.1% to 148,350 (Knight Frank, Q2 2026, citing UCAS). By results day, a record 446,690 applicants had been accepted (UCAS, August 2026).
Occupancy, rental growth and returns
Well-located schemes have let almost every bed in recent years: Unite Group reported 97.5% occupancy and 8.2% rental growth for 2024/25 (Unite Group, February 2026). Income is the core of the return. CBRE's UK PBSA Index recorded a 5.4% income return in the year to September 2025, although a 2.0% fall in capital values cut the total return to 3.4% (CBRE, 2025). Rents are reset every year, so income can respond to inflation faster than long commercial leases.
Liquidity and depth
The investment market is deep. Investors committed £4.3bn to UK PBSA in 2025, up 10% on the year, across 79 deals (Knight Frank, February 2026), and £2.3bn in the first half of 2026 (Knight Frank, Q2 2026). That depth supports exit strategies and makes PBSA easier to value and finance than many alternative assets.
How do property investors get exposure to PBSA?
Professional property investors reach the sector in several ways, each with a different risk and return profile and a different strategy for exit:
- Develop and hold or sell. A developer buys a site, secures planning, builds with development finance and either holds the completed scheme or sells it to an institution. This carries the most risk and the highest potential return.
- Forward funding and joint ventures. An investor funds construction in return for the completed asset, or partners with a developer or university. Knight Frank recorded a record number of funding deals and joint ventures in 2025, 16 of the 79 transactions (Knight Frank, February 2026).
- Buy operational assets. The most common route: operational assets made up 64% of transactions in the first half of 2026 (Knight Frank, Q2 2026). Investors buy trading income and a known track record.
- Listed companies and funds. Shares in listed student accommodation owners, or units in property funds, give liquid exposure without owning a building, with share price volatility as the trade-off.
- Debt. Banks, debt funds and insurers lend to the sector, taking a secured, income-based position below the equity.
Each route shapes what an investor must consider: development risk, operator selection, leverage, and how easily the investment can be sold.
What are the risks of PBSA investment?
Oversupply in some cities
National undersupply hides local variation. Occupancy across the wider PBSA sector averaged around 86% in 2025/26, and Unite's vacancies were concentrated in Leicester, Nottingham and Sheffield, where weaker demand combined with high levels of existing and new supply (Unite Group, February 2026). Rental growth across all room types slowed to 2%, with marginal rent declines in Sheffield, Nottingham, Leeds and Glasgow, and incentives worth 4.2% of advertised annual rent (Knight Frank, 2025/26). BONARD's figures point the same way: a pipeline of around 176,000 beds against around 755,000 beds analysed (BONARD, September 2026). Location is the first question in any PBSA deal.
International student policy
International students are a large share of direct-let demand, particularly for studios and in London. Policy has tightened. Most students lost the right to bring dependants from 1 January 2024. The Graduate Route falls from two years to 18 months for applications from 1 January 2027 (Home Office, October 2025), and an international student levy of £925 per international student per year takes effect in England from 1 August 2028 (GOV.UK, July 2026). Sponsored study visa applications from main applicants were 16% lower in the year to August 2026, at 360,700 (Home Office, September 2026). Any further change to visas or post-study work rights feeds straight into demand.
Affordability and commuter students
HEPI notes that the maximum maintenance loan in England is £10,500, around half of what its research suggests a student needs to live on (HEPI, April 2026), and more students are choosing to live at home. The share of June UCAS applicants intending to live at home rose to 35% in 2026 (Knight Frank, Q2 2026, citing UCAS). Rents cannot rise faster than students can pay for long.
Regulation
The Renters' Rights Act 2025 took effect for tenancies in England on 1 May 2026. PBSA let by members of an approved code can stay outside the new periodic tenancy regime, which makes code membership a condition of the investment case (Unipol, 2026). See our Renters' Rights Act guide.
Building safety and construction costs
Tall student accommodation is a higher-risk building under the Building Safety Act 2022. Gateway 2 approval added months to programmes; the median time for new higher-risk buildings was 22 weeks in the 12 weeks to August 2026, down from 43 weeks a year earlier (Building Safety Regulator, 2026). Build cost inflation and finance costs are squeezing development viability (Knight Frank, Q2 2026). See the Building Safety Act and Gateway 2.
Operator and pricing risk
PBSA income is only as good as the operator running the building. Weak marketing, poor maintenance or the wrong pricing can empty a well-located scheme. Yields can also move: Knight Frank's prime direct-let yields widened from around 4.50% in London in Q1 2026 to around 4.75% in Q2 2026 (Knight Frank, 2026), and a rise in yields reduces capital value even when income holds.
Should private investors buy a student pod?
Retail student property schemes sell individual rooms, often called student pods, to private investors, usually on a long lease with a promised return for the first few years. They are marketed on the strength of the institutional market described above, but they are not the same investment.
We do not provide investment advice and we do not arrange finance for individual student rooms. The points below are general risks, not a recommendation. Take independent regulated advice and legal advice before committing money.
- Assured returns are often funded from the purchase price rather than from rent, and can stop when the guarantee period ends or the developer fails.
- You own one room, not the building. You depend on the freeholder and operator for management, maintenance and lettings, and pay their fees and service charges.
- Resale is difficult. Mainstream lenders rarely lend against a single student room, so buyers are few and usually cash-only.
- Off-plan risk. Many schemes are sold before the building is finished. If the developer becomes insolvent, deposits and stage payments can be lost.
- Limited protection. Direct property purchases are generally outside the Financial Services Compensation Scheme. Check any firm on the FCA register and read the FCA's ScamSmart guidance on investment scams.
Institutional investors get exposure to the same demand drivers with full due diligence, control of the building and a liquid exit. For private investors, listed student accommodation companies offer a more liquid route, though with share price risk of their own.
How does PBSA compare with traditional buy-to-let?
PBSA differs from buy-to-let in scale, tenancy and management. Traditional buy-to-let residential property earns rent from one household on an assured tenancy, with a landlord or agent managing it. A student HMO sits between the two. Purpose-built student accommodation earns rent from hundreds of students on annual contracts, with a professional operator and a building designed for the purpose.
| Institutional PBSA | Student HMO | Traditional buy-to-let | |
|---|---|---|---|
| Income | Many rooms, reset each academic year | Several rooms, yearly tenancies | One household, longer tenancies |
| Void periods | Summer, unless let for 51 weeks or to summer guests | Summer voids common | Between tenancies |
| Management | Specialist operator | Landlord or agent | Landlord or agent |
| Valuation basis | Capitalised net operating income | Investment value or bricks and mortar | Bricks and mortar |
| Finance | Commercial development and term debt | HMO mortgage | Buy-to-let mortgage |
Rental yields on PBSA are quoted as net initial yields after operating costs, while buy-to-let yields are usually gross, so headline numbers are not comparable. Our guide to PBSA yields explains the difference, and PBSA vs student HMO compares the two student models.
What is the outlook for student accommodation investments?
The 2026 picture is mixed. Investors committed £2.1bn in Q1 2026, the strongest start to a year in more than a decade, helped by Unite Group's purchase of Empiric Student Property (Knight Frank, Q1 2026). Activity then slowed to £164m in Q2, one of the lowest quarters on record, as buyers and sellers disagreed on price, although Knight Frank was tracking more than £1.5bn of assets under offer (Knight Frank, Q2 2026).
Supporting the case: record UCAS applications, new supply of 19,200 beds in 2025, below the ten-year average of about 21,000 beds a year, and a Bank Rate held at 3.75% in July 2026 with the prospect of lower borrowing costs over time (Knight Frank, Q2 2026). Against it: softer occupancy in some regional cities, affordability pressure and policy risk on international students. The market's resilience rests on the strongest locations and the best-run buildings, not on the sector as a whole.
Outside London, the main regional markets for PBSA investment include Manchester, Birmingham, Leeds, Bristol, Liverpool and Newcastle, each with large universities and an established stock of operating schemes to compare against.
Investor sentiment and yields are tracked city by city in our PBSA Capital Monitor.
What do lenders look for in a student accommodation investment?
A lender's credit process is a useful, unsentimental test of any PBSA investment strategy. Before advancing investment or acquisition debt, typically at 55 to 65% LTV and subject to status, valuation and lender criteria, lenders ask:
- Location. How deep is student demand in this city, how does the student-to-bed ratio look, and what is in the planning pipeline?
- Trading history. What occupancy and rental growth has the building achieved, and how does it compare with nearby schemes?
- Income quality. What share is direct let, what share is under nomination agreements, and how long do those run?
- Operator. Who runs the building, what is their track record and what are the fees?
- Building. Is it compliant with building safety requirements, and what lifecycle capital spend is coming?
- Cover. Does net operating income cover interest comfortably, and what is the debt yield?
We arrange finance for PBSA developers, operators and investors; we are not a lender. For how debt is sized on a trading scheme, see PBSA investment finance, or test the numbers with our debt sizing tool. For the current state of demand and supply, see the UK PBSA market and the PBSA Capital Monitor.
Questions
Why invest in PBSA?
Is student accommodation a good investment in the UK?
Is student accommodation a high risk building?
What is a student pod investment?
Are PBSA yields higher than buy-to-let?
- UCAS, Quarter of a million UK 18-year-olds gain place at university or college, 13 August 2026
- Savills, UK cities need much higher rates of student housing delivery, April 2024
- Unite Group, 2025 full-year results statement, February 2026
- CBRE, CBRE reports positive total returns for PBSA despite market challenges (year to September 2025)
- Knight Frank, UK Student Accommodation Outlook 2025/26
- BONARD, UK PBSA Report 2026, September 2026
- Home Office, Monthly entry clearance visa applications, August 2026
- Home Office, Explanatory memorandum to the Statement of Changes to the Immigration Rules HC 1333, October 2025
- GOV.UK, Introducing an international student levy on higher education providers, July 2026
- Knight Frank, UK Student Market Update Q4 2025 (February 2026)
- Knight Frank, UK Student Market Update Q1 2026
- Knight Frank, UK Student Market Update Q2 2026
- HEPI, Weekend reading: what's happening with the UK's student accommodation?, April 2026
- Unipol, Students in private sector purpose-built accommodation (Renters' Rights Act 2025)
- Building Safety Regulator, building control approval application data, May to July 2026
- Home Office, Changes to student visa route will reduce net migration, May 2023
- FCA, ScamSmart
 Written and reviewed by Matt Lenzie, Founder and principal. Last reviewed .